
Have you ever caught yourself holding your breath while opening a banking app, or felt a knot in your stomach while paying for groceries? For many of us, managing money feels less like solving a math problem and more like riding out a wave of quiet anxiety. We’re taught that financial stability is a matter of arithmetic — add, subtract, follow the spreadsheet. But knowing basic math rarely prevents financial stress.
Our relationship with money is deeply psychological. How we earn, save, and spend is shaped not just by logic, but by early experiences and the beliefs we form about safety and security. When a persistent feeling of “not enough” takes root, it can be hard to feel secure — even once our circumstances improve.
Unlearning that response doesn’t mean ignoring financial reality or making reckless choices. It means learning to tell genuine financial concerns apart from old fear, and reacting to today instead of yesterday.
Where Financial Anxiety Really Comes From
When money feels overwhelming, it’s easy to default to self-blame — not enough discipline, not enough skill, not enough self-control. But financial decisions are shaped by far more than numbers.
Take two people with nearly identical incomes and the same savings balance. One sees it as a solid safety net. The other can’t shake the feeling that it could vanish any moment. Same numbers, completely different relationship with them — because the numbers were never really the point.
Recognizing this psychological layer shifts the focus from self-blame to self-awareness. Once you know what actually triggers your money stress, you can build habits that make it feel more predictable.
Scarcity Isn’t the Same as Hardship
It’s worth being honest here: a scarcity mindset and genuine financial insecurity are not the same thing.
If your income doesn’t reliably cover essentials, you’re carrying serious debt, or an unexpected bill has knocked you sideways, worrying about money is a reasonable response to real circumstances — not a mindset problem. No amount of reframing replaces actual income or manageable expenses.
The goal isn’t to convince yourself everything’s fine when it isn’t. It’s to deal with real problems practically, without letting fear drive every decision on top of them.
Why Money Stress Fogs Your Thinking
Financial worry is exhausting partly because it competes for your attention. Researchers Sendhil Mullainathan and Eldar Shafir describe scarcity as something that eats up mental “bandwidth,” leaving less room for everything else.
A widely cited 2013 study in Science found that thinking about a difficult financial problem measurably affected cognitive performance among lower-income participants. The same researchers studied sugarcane farmers in India and found their cognitive test scores shifted depending on whether they were tested before or after harvest — when their financial pressure eased.
The takeaway isn’t that financial stress makes you less intelligent. It’s that ongoing money worry consumes attention, making everything else harder to focus on. That’s often why someone who’s normally a careful planner suddenly procrastinates on bills or grabs short-term relief over a smarter long-term fix. It’s not a character flaw — it’s a bandwidth problem. The fix is usually to simplify the system, not to try harder.
The Beliefs You Inherited About Money
Many of our money beliefs started with what we saw growing up — often called “money scripts” in financial psychology, a term from research by Brad Klontz and Sonya Britt. These are largely unconscious ideas that quietly steer financial behavior.
Researchers describe four broad patterns:
- Money avoidance — believing money is bad or that you don’t deserve it, which can lead to underspending even on real needs.
- Money worship — believing more money will finally fix things, which can drive overspending or overworking chasing that feeling.
- Money status — tying self-worth to net worth or possessions.
- Money vigilance — watching every dollar closely, sometimes to the point of anxiety even when finances are stable.
These aren’t diagnoses — they’re patterns, and most people carry a mix. A useful question: is this belief helping me today, or is it an echo of a situation I’ve already outgrown?
Healthy Caution vs. Unhelpful Scarcity
Letting go of scarcity thinking doesn’t mean dropping sensible precautions. There’s a real difference between being careful with money and feeling permanently threatened by it.
Healthy caution is grounded in current facts: you save because unexpected costs happen, you compare prices because you want value, you delay a purchase because it isn’t a priority right now.
Unhelpful scarcity feels different. You keep worrying even after building a solid cushion. You feel guilty over spending you can clearly afford. You avoid checking your accounts because it feels like too much. The goal isn’t to stop caring — it’s to base decisions on what’s actually true today, not what felt true once.
Three Small Habits That Actually Help
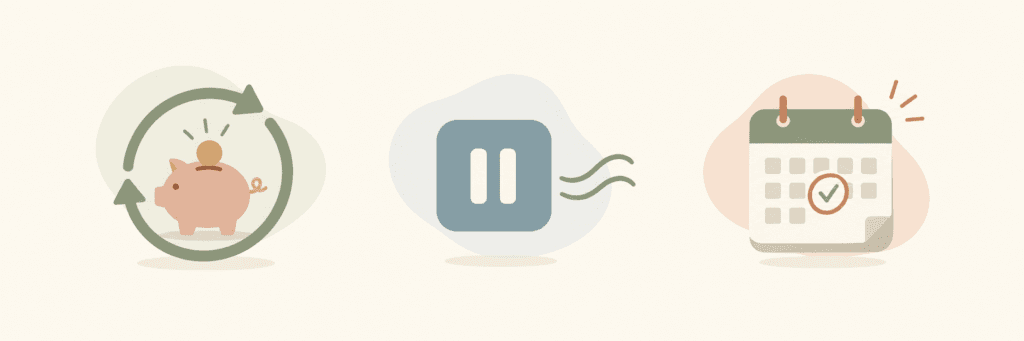
1. Automate the boring stuff. Set an automatic transfer to savings after payday, automate recurring bills, and build a small emergency fund on autopilot. Fewer decisions means fewer chances for anxiety to hijack them.
2. Try Notice → Pause → Check → Choose. When a bill or purchase suddenly spikes your anxiety: notice what you’re feeling, pause for a few breaths, check the actual numbers — balance, bills, budget — then choose one sensible next step. Instead of spiraling into “I can’t afford anything,” you find out what’s really driving the worry.
3. Run a weekly 10-minute money check-in. Rather than obsessively checking your accounts or avoiding them entirely, pick one calm window each week to review balances, upcoming bills, and savings progress, then decide on one action. This turns money management into routine, not crisis response.
The Goal Isn’t Perfect Certainty
A healthier relationship with money isn’t about becoming careless or pretending problems don’t exist. It’s about separating real financial facts from inherited fear.
You can build an emergency fund and still enjoy spending. You can stay cautious without treating every purchase as a threat. You can notice the money beliefs you grew up with — without letting them run the show.
You don’t need certainty to feel confident with money. You need enough awareness and structure that money becomes something you manage, instead of something that manages you.
What’s one money belief from your childhood you’re still carrying around? Worth sitting with this week.