
There’s a particular kind of payday feeling most of us know. The money lands, you feel briefly rich, and by the second week you’re wondering where it all went.
Nothing dramatic happened. No big purchase, no emergency. Just a hundred small decisions that each felt reasonable at the time.
When that keeps happening, it’s easy to decide the answer is more discipline: tighter rules, stricter budgets, a little guilt on the side. But willpower is a tiring way to live, and it usually runs out by Friday.
Here’s the gentler truth: people who save a lot rarely rely on willpower. They set up a few boring systems that quietly do the work, then get on with their lives.
This isn’t a strict plan or a competition. Take the habits that fit your life and leave the rest. If saving 50% feels impossible right now, that’s completely okay. A common rule of thumb is to save around 20%, and even 5% is a real start. These 10 habits work at any percentage.
I’m not a financial advisor, just someone who believes small, boring habits beat big, dramatic plans.
1. Automate your savings on payday
Set up an automatic transfer to a separate savings account on payday, before you can spend it. It works the way rent does: a set amount moves first and you live on the rest. Why “paying yourself last” keeps you stuck
2. Think in hours of work, not prices
Before a non-essential purchase, convert the price into hours of your work, using your take-home pay for the most honest number. A 120 pair of shoes sounds small until you realize it’s about eight hours of your life if you take home 15 an hour. Sometimes it’s still worth it, and sometimes the answer becomes obvious the moment you do the math.
3. Wait 48 hours before non-essential purchases
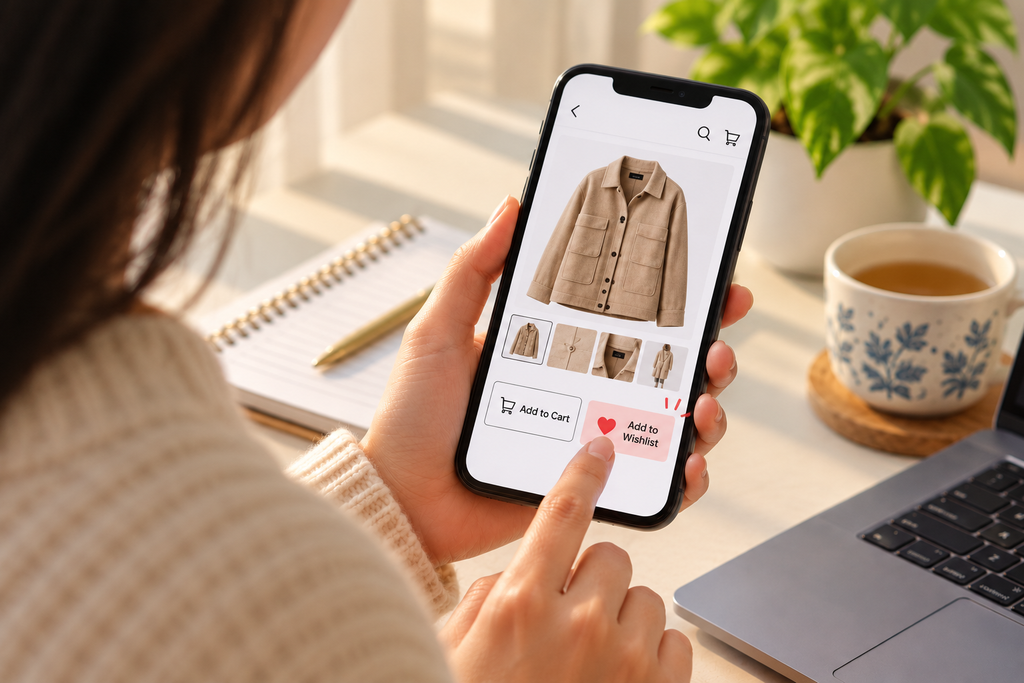
Write the item down and come back in two days. If you still want it after 48 hours, buy it without guilt. You know the 11 p.m. moment: the perfect jacket is in your cart and it suddenly feels urgent. Screenshot it, close the app, and look again on Thursday. Often the urge has moved on without you.
4. Plan your meals for the week
Food is one of the easiest places to overspend without noticing. A short weekly plan and a grocery list cut down on takeaway, impulse snacks, and wasted food. Ten minutes on Sunday gets you four dinners and one list. By Wednesday, you’re not standing in the kitchen at 8 p.m., hungry and ordering takeaway because there’s “nothing to eat.”
5. Audit your subscriptions every month
Set a recurring ten-minute reminder to scan your statement for forgotten charges, like the streaming service that’s still billing you months after the finale. Cancel anything that doesn’t earn its place. More spending that rarely earns its place
6. Keep a small fun-money allowance
Strict budgets collapse when they leave no room for joy. Give yourself a set amount to spend however you like, no explanations needed. Maybe it’s a small weekly amount for a latte, a paperback, or a night out. Because it’s planned, it feels like a treat instead of a slip, and it keeps every other habit sustainable.
7. Set aside money for irregular costs
Insurance renewals, gifts, repairs, and annual fees only feel like emergencies when they surprise you. Divide each one by 12 and set that amount aside every month in a separate pot, often called a sinking fund. If your insurance renewal is 1,200 a year, setting aside 100 a month means the bill arrives and nothing breaks.
8. Review your biggest expenses once a year
Saving half is hard if housing, transport, and debt take most of your income, so once a year, ask whether you can renegotiate, switch providers, or reduce one of them. One 30-minute call about a phone or internet plan can sometimes save more than months of skipping small treats. A step-by-step look at lowering your biggest bills
9. Borrow, rent, or buy secondhand first
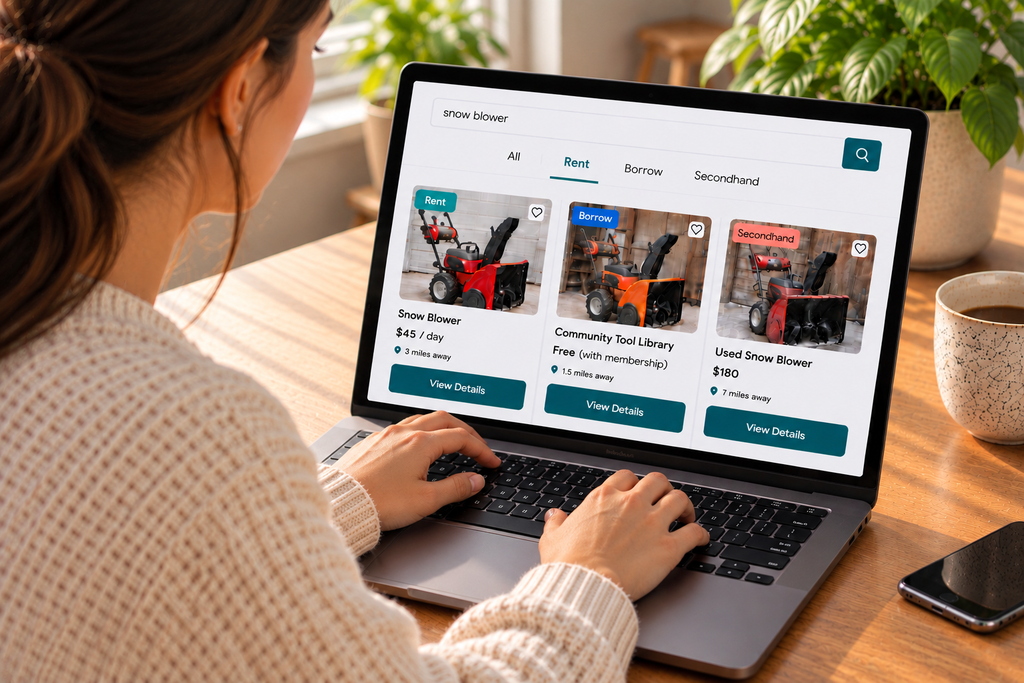
For things you’ll use rarely or briefly, check whether you can borrow, rent, or buy secondhand before buying new. Think of the drill you’ll use twice a year, the outfit for one wedding, or the camping gear for a single trip. Some libraries and community groups lend tools and equipment, and secondhand marketplaces make the rest easy to find.
10. Save half of every raise
When your income goes up, send at least half of the increase to savings before your lifestyle adjusts. Say you get a raise next year: half goes straight to savings, and the other half makes life a little nicer. Your savings rate climbs without it ever feeling like a sacrifice. More on how lifestyle creep sneaks in
A reality check about saving 50%
Saving half your income depends on your income and fixed costs, not only your habits. Some people can’t get there right now, and that isn’t a personal failing. If your bills take most of your money, focus on lowering one big expense or raising your income, and start with a savings rate you can actually hold. Any consistent amount counts.
Frequently asked questions
Is it realistic to save 50% of your income? For some people, yes, usually with low fixed costs, a higher income, or both. For many others, a smaller percentage is more realistic. Start with what’s sustainable and increase it gradually.
What’s the easiest way to start saving more money? Automate a small transfer to a separate account on payday. It takes about five minutes to set up and works without willpower.
How much should I save each month? A common rule of thumb is around 20% of your income, but the right amount depends on your costs, debts, and goals. Starting at any percentage beats waiting for a perfect one.
Start with one boring habit
You don’t need to do all ten this week. Pick one, set it up today, and let it run. Boring habits don’t feel exciting while you build them. A few months later, they start to look a lot like freedom.
This article is for general information and is not financial advice.