
Have you ever looked at your bank account and thought, “Where did all my money go?”
Not because you bought a new car. Not because of one huge shopping trip.
It was probably the $12 here, the $19 there, the subscription you forgot about, the delivery order you placed because you were too tired to cook, or the “great deal” you bought and barely used.
That is the frustrating thing about wasting money. It rarely feels like wasting money when you’re doing it.
And in 2026, when everyday expenses already take a noticeable bite out of a household budget, being a little more intentional can make a real difference.
This does not mean you have to stop enjoying your money.
It simply means spending it on things that actually make your life better.
Here are seven expenses worth looking at a little more closely.
1. Subscriptions You Barely Use
This one is almost too easy.
You signed up for a streaming service because everyone was talking about a new show. Then you signed up for another one because the first service didn’t have something you wanted to watch.
Then there is the meditation app you used for four days.
The workout membership you swore you’d use every morning.
The meal-planning app.
The software subscription.
The free trial you forgot to cancel.
Individually, these charges don’t look scary. Together, they can become a monthly bill for services you barely think about.
Try this tonight: open your bank or credit-card app and search your recent transactions for recurring charges.
For every subscription, ask:
“Would I pay for this again today?”
If the answer is no, cancel it.
You are not losing anything by getting rid of something you aren’t using.
2. Extended Warranties on Things You Could Easily Replace
You’re standing at the checkout counter buying a $100 appliance, and the cashier asks:
“Would you like the protection plan?”
Suddenly, spending another $15 or $20 feels like the responsible thing to do.
But protection plans aren’t automatically worth buying.
For inexpensive products, you may end up paying for coverage you never use—and dealing with deductibles, exclusions, or complicated repair rules.
That doesn’t mean every warranty is a waste.
For something expensive, complicated, or costly to repair, additional protection may make sense.
The point is to stop buying a warranty automatically just because you’re nervous about something breaking.
Before saying yes, look at what the manufacturer’s warranty already covers and what the extra plan actually gives you.
3. Buy Now, Pay Later for Something You Don’t Really Need
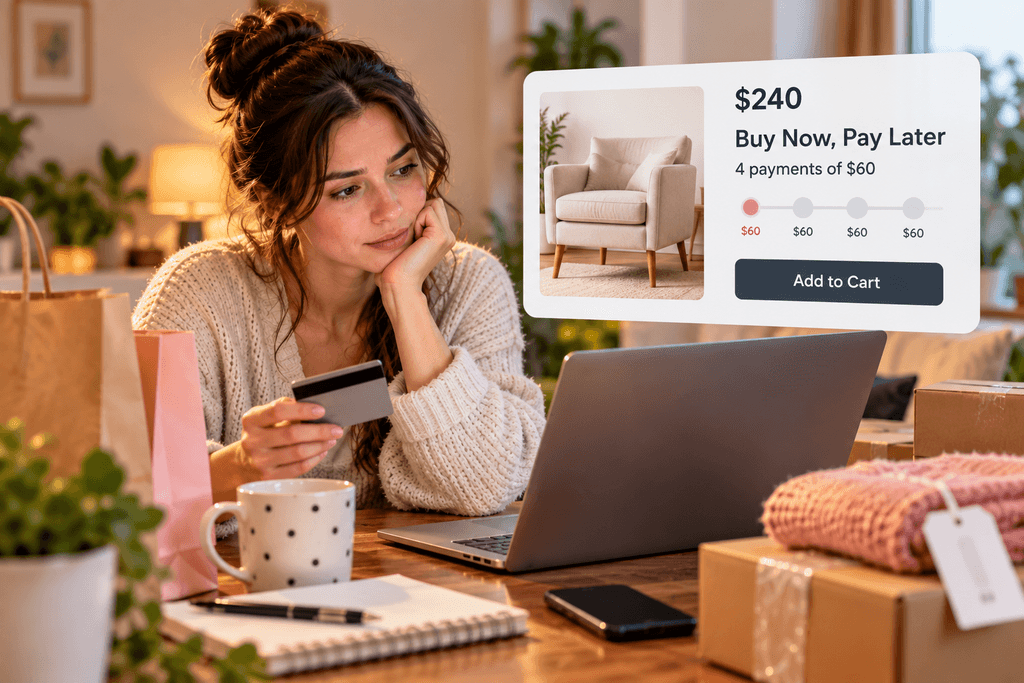
Let’s say you see a $240 chair online.
You don’t really have $240 to spare, but the website says:
“4 payments of $60.”
That suddenly sounds manageable.
And this is where things can get tricky.
The payment might fit into this week’s budget even though the entire purchase does not fit into your actual financial life.
A useful rule is simple:
If you wouldn’t buy it with the full price in your head, don’t buy it because the payment looks small.
There are situations where splitting a purchase into payments can be useful.
But using financing to make unnecessary purchases feel affordable is a habit worth breaking.
4. Food Delivery When You’re Paying More Out of Habit
Picture this.
It’s Wednesday night. You’ve had a long day. You get home, open your phone, and order dinner.
Completely reasonable.
Then Friday comes around, you’re tired again.
Sunday arrives, and cooking feels like too much work.
Suddenly, what started as an occasional convenience has become three delivery orders a week.
The problem isn’t the occasional $25 dinner.
It’s the repetition.
Delivery fees, service charges, tips, and higher online prices can turn an ordinary meal into a much more expensive one.
You don’t have to stop ordering food.
Just make convenience a conscious choice instead of the default.
One simple habit: before checking out, look at the final total and ask, “Would I still order this if I had to pick it up myself?”
Sometimes the answer will still be yes.
That’s fine.
The goal isn’t guilt. It’s awareness.
5. Bottled Water When You Already Have Safe Tap Water
Walk into a grocery store and a case of bottled water can feel like one of those things you automatically put in the cart.
But if your home’s tap water is safe to drink, repeatedly buying disposable bottles may not be the most sensible way to spend your money.
A good reusable bottle costs far less over time.
And if you don’t like the taste of your tap water, a suitable home water filter may be a better long-term option.
Of course, water quality varies by location, so check your local water-quality information before making changes.
This isn’t about never buying bottled water.
It’s about not paying again and again for something you can already get at home.
6. Trendy Things You Loved on TikTok for About Two Weeks
We’ve all done this.
You see a beautiful kitchen gadget online.
Everyone seems to own the same sneakers.
Suddenly you need the viral organization bins, the fancy tumbler, the beauty tool, the decorative lamp, or the latest wellness gadget.
Three weeks later?
It’s sitting in a drawer.
Before buying a trend, give yourself a little breathing room.
Ask:
“Would I want this if I hadn’t seen it online?”
And:
“How often am I realistically going to use it?”
A cheap item you use every day can be a great purchase.
A $70 item you use twice isn’t.
7. Paying Extra for Convenience You Don’t Really Value
Modern life makes it incredibly easy to pay someone—or a company—to make small things easier.
Premium delivery.
A short rideshare instead of a 10-minute walk.
Pre-cut fruit.
Same-day shipping.
Another coffee because you didn’t want to make one at home.
Again, there is nothing wrong with paying for convenience.
Sometimes your time is absolutely worth the money.
The problem starts when every little inconvenience gets solved with your wallet.
Try creating a small monthly “convenience budget.”
Spend it freely without feeling guilty.
But once you’ve used it, pause before adding another convenience purchase.
It makes you notice which conveniences genuinely improve your life—and which ones you barely remember five minutes later.
The Real Goal Isn’t to Spend Less on Everything
You don’t need to become someone who tracks every coffee and refuses to enjoy a dinner out.
That kind of budgeting can become exhausting.
Instead, look for the expenses that don’t give you much back.
A subscription you forgot about.
A purchase you barely use.
A convenience charge you don’t really appreciate.
A trendy item you wanted for a week.
Those are often much easier to cut than the things that genuinely make your life happier.
Before spending money, ask yourself four questions:
Do I need it?
Will I actually use it?
Does it make my life meaningfully better?
Can I comfortably afford it?
You don’t need four yeses every time.
But when most of the answers are no, your future self will probably be happier that you waited.
Because being good with money isn’t about never spending.
It’s about being able to look at your spending and feel like your money is going toward the life you actually want.